A twin cities hail roof insurance claim starts with documenting damage before calling your carrier. Here is what the process actually looks like, step by step.
A twin cities hail roof insurance claim is not a process most homeowners have done before, and the first decision shapes everything that follows. Whether you document damage independently before contacting your carrier, or call the insurance company the morning after the storm without any information of your own, determines how well-positioned you are when the adjuster arrives. Minnesota sees significant hail activity between April and September, and homeowners across Minneapolis, St. Paul, Plymouth, Maple Grove, Edina, and surrounding suburbs face the same sequence of questions with limited time to get the answers right. This guide covers what the process actually looks like, from confirming you have damage worth claiming to selecting a contractor once a settlement is in hand.
Do You Actually Have Hail Damage Worth Claiming?
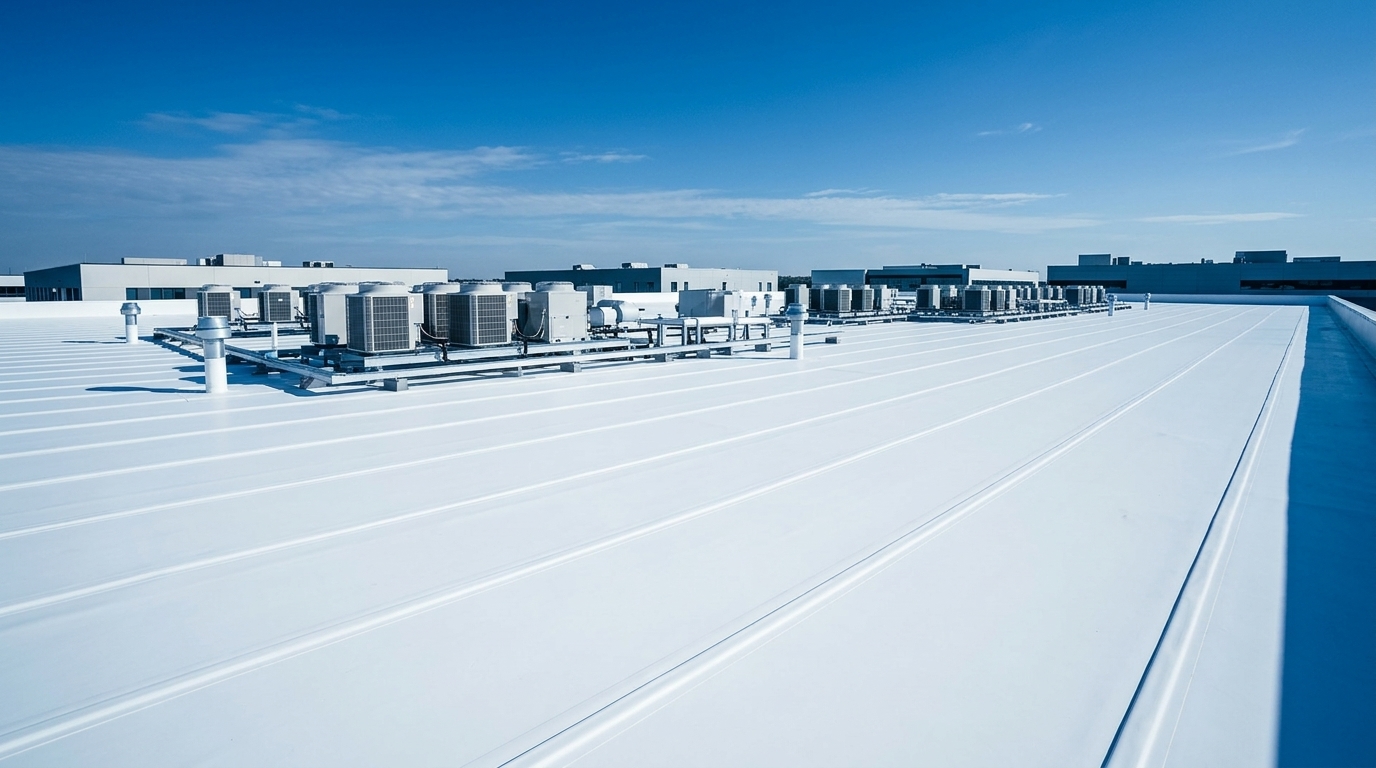
The first question is not whether hail hit your area. It is whether your specific roof took damage significant enough to support a claim that makes financial sense relative to your deductible. A twin cities hail roof insurance claim is evaluated on the actual condition of your specific roof, not your neighbor's approval or the size of hail on a local weather map. Hail damage that warrants a claim typically shows consistent impact bruising across multiple roof faces, soft metal evidence on vents and flashing, and granule loss that has exposed the fiberglass mat rather than just thinning the surface.
Getting an independent inspection and written assessment before contacting your carrier gives you a factual baseline to compare against the adjuster's findings. Not every roof hit by hail has damage worth claiming. A five-year-old architectural shingle that absorbed a storm without mat fracturing is in a different position than a twenty-year-old shingle showing widespread impact bruising. David inspects roofs across the Twin Cities and provides homeowners an honest assessment of what is on the roof before any claims conversation begins. Schedule a storm damage inspection to get that baseline first.
How to File a Hail Damage Roof Claim in Minnesota
The mechanics of filing a hail damage roof insurance claim in the Twin Cities are straightforward, but the timing and documentation quality at each step matter. Here is the sequence most Minnesota homeowners follow.
- Get an independent inspection first. Before contacting your carrier, schedule a professional inspection from a local licensed roofing contractor. A written damage assessment with photographs gives you a record of what was found on your roof before the insurance process begins.
- Review your policy. Pull your policy documents and confirm your deductible structure, filing window, and any wind and hail-specific terms. Some policies carry percentage-based deductibles tied to the insured value of the home rather than a flat dollar amount.
- Contact your insurance agent before the main claims number. Your agent can walk you through your specific coverage terms and help you understand what to expect before you formally open a claim.
- Open the claim once you have your documentation and understand your policy terms. Your carrier will assign an adjuster and schedule a roof visit.
What Happens at the Adjuster Meeting
The adjuster visit is where your independent documentation matters most. An insurance adjuster will assess your roof to determine the scope and cause of damage from the carrier's perspective. Having your own inspection report and photographs means you can compare their findings against what an independent roofer documented before the visit.
David meets the adjuster on every twin cities hail roof insurance claim we are involved with. Walking the roof together with the adjuster means damage that might otherwise be overlooked, soft metal evidence on step flashing, impact bruising on north-facing slopes, and granule loss in less prominent areas, gets reviewed in real time rather than appearing only in your independent report as an after-the-fact comparison.
If the adjuster's report and your independent inspection differ significantly in scope, note the specific discrepancies before the claim is settled. You have the right to present additional documentation and, in some cases, to request a re-inspection through your carrier's claims process.
When Your Initial Settlement Looks Too Low
A supplement is an additional claim submission that documents damage or replacement scope not included in the initial adjuster report. Twin cities hail roof insurance claim supplements are common and legitimate. They happen when an adjuster misses line items, when material pricing has changed between inspection and settlement, or when additional damage is discovered during the actual roof repair work.
Supplement items commonly include code upgrade requirements for your municipality, accessory materials not accounted for in the initial scope, and cost adjustments tied to current market pricing. Supplements are not inflated claims. They are documentation of scope that was missed or undervalued in the initial settlement, and your carrier reviews them through their standard process.
How to Choose a Contractor for Your Hail Claim Repair
Choosing a contractor for a twin cities hail roof insurance claim repair carries more weight than a standard roofing project, because the contractor you select works from the insurance scope and is responsible for delivering the result your policy paid for.
Verify the Minnesota contractor license first. The Department of Labor and Industry maintains a public license lookup. Any contractor who cannot produce a verifiable Minnesota license number is not authorized to perform licensed roofing work in this state.
Avoid contractors who offer to waive your deductible. This is illegal under Minnesota law. A contractor who makes this offer is either uninformed about state law or comfortable with practices that create legal liability for the homeowner.
Choose a contractor with a physical local presence. A company based in the Twin Cities metro has a stake in the work they do here. Out-of-state storm chasers who follow hail events typically prioritize volume and move on, leaving homeowners with limited recourse when issues surface after they leave the area.
Altus Construction is Minnesota-licensed, owner-led, and based in St. Louis Park. David handles every project personally. If you have questions before scheduling, reach out through our contact page.
The Realistic Timeline for a Twin Cities Hail Claim
A twin cities hail roof insurance claim that moves efficiently from inspection through completed repair typically takes four to ten weeks, though the timeline varies based on storm volume, carrier workload, and how quickly each step is completed. Here is a realistic sequence.
- Weeks one to two: independent inspection and documentation, policy review, decision to file.
- Weeks two to three: claim opened with carrier, adjuster visit scheduled.
- Weeks three to five: adjuster report received, scope comparison completed, supplement review if needed.
- Weeks five to eight: contractor selected, materials ordered, installation scheduled.
- Weeks eight to ten: installation completed, warranty documentation finalized.
Filing delays, adjuster availability during high-volume storm seasons, and material lead times can extend this timeline, particularly after a storm that affects a large portion of the metro at once. Moving through the early documentation steps promptly keeps more of the timeline within your control.
If your Twin Cities home went through a hailstorm this season and you are weighing whether a claim makes sense, accurate damage documentation is the starting point, not a filing decision made without information. Altus provides roof inspections across the Twin Cities metro with written assessments and photo documentation you can take to your carrier. Book your inspections appointment and get the facts about your roof before deciding what to do next.
Visit us in St. Louis Park, MN, we are a local, licensed team that meets adjusters, documents damage honestly, and works on your timeline.
Frequently Asked Questions
How do I know if my Twin Cities roof has hail damage worth claiming?
The threshold question is whether the documented repair or replacement cost meaningfully exceeds your deductible and whether the damage affects functional waterproofing rather than only cosmetic granule coverage. A roof with widespread impact bruising and mat fracturing on a shingle system near end of life is a different situation than a newer roof with minor surface granule loss. An honest independent inspection gives you the specific facts to make that judgment before contacting your carrier.
How long do I have to file a hail damage roof claim in Minnesota?
The filing window varies by carrier and policy. Pull your policy documents and confirm the deadline with your insurance agent rather than relying on general guidance. The practical reason to move promptly is documentation quality. The ability to connect specific damage to a specific storm becomes harder as additional weather occurs and the roof weathers further. An inspection completed shortly after the storm produces stronger documentation than one done months later.
Will filing a twin cities hail roof insurance claim raise my premiums?
Whether a weather-related claim affects future premiums depends on your specific carrier and their claims history policies. Some carriers treat hail and wind claims differently from claims tied to homeowner negligence, since the storm is outside your control. Others factor any claims activity into future rate adjustments. This is a question worth asking your insurance agent before filing so you can weigh potential premium impact against the value of the claim. Altus documents the damage; premium decisions belong between you and your carrier.
Should I get an inspection before or after contacting my insurance company?
Before. Having your own independent inspection and documentation before your carrier's adjuster visits gives you a factual baseline to compare against their findings. If the adjuster's report differs from your inspection in scope, you have specific documentation to present when requesting review. Homeowners who contact their carrier first and schedule an inspection only after the adjuster has already visited are working backward through the information sequence.
Can Altus meet my adjuster during the twin cities hail roof insurance claim process?
Yes. David meets the adjuster on every storm claim where Altus is involved. Being on the roof together when the adjuster inspects means damage documentation happens in real time, with both parties reviewing the same surfaces at the same time. Soft metal evidence, impact bruising on less prominent faces, and scope items that might be missed during a solo adjuster visit get reviewed together rather than appearing only in your independent report as a comparison after the fact.
David Armenta Magana, Owner.